Categories
Featured Ideas & Insights

PENGERANG INTEGRATED PETROLEUM COMPLEX (“PIPC”)
Special Incentive Package for Manufacturing Sector

PENGERANG INTEGRATED PETROLEUM COMPLEX (“PIPC”)
Special Incentive Package for Manufacturing Sector

PIPC offers highly attractive tax incentives packages for manufacturing investors, including up to 10 years of income tax exemption, customs duty exemptions on importation of machinery, equipment and raw materials and reduced tax rates on qualifying activities.
Strategically located in Johor, Malaysia, the Pengerang Integrated Petroleum Complex (PIPC) is a fully integrated oil and gas megaproject that positions Malaysia as a leading energy and petrochemical hub in Southeast Asia. With world-class infrastructure, deepwater port access, and strong government support, PIPC offers investment opportunities in the downstream and midstream sectors.

Attractive Tax Incentives

Incentive Type
Details

1.

Special Income Tax Rate
  • 5% or 10% tax rate for up to 10 years on qualifying income; OR

2.

Investment Tax Allowance (ITA)

  • 60% or 100% capital expenditure allowance for up to 10 years;
  • Offset up to 100% of statutory income for each assessment year.

Import Duty and Sales Tax Exemptions

Exemptions on machinery, equipment, raw materials, and components used in qualifying manufacturing activities.

Stamp Duty Exemptions

Potential exemptions on property transfers and loan agreements related to approved projects.

Eligible Activities and Products

Production and processing of chemical and petrochemical products:-
i. Base Chemical – Methanol, Ethylene, Propylene, Benzene, Aromatics
ii. Organic Intermediates – C1 to C6 ;
iii. Specialty Chemical;
iv. Fertilisers;
v. Polymers/ Plastics;
vi. Oleochemical/ Biochemical

Who Can Apply

  • Local and foreign companies incorporated in Malaysia;
  • A minimum capital investment of RM500 million in qualifying manufacturing activities within PIPC.
This incentive is eligible to be considered for application received by Malaysian Investment Development Authority (“MIDA”) from 14th October 2023 to 31st December 2028.
Categories
Featured Ideas & Insights

Automation Capital Allowance (Automation CA) For Manufacturing And Services Sectors

AUTOMATION CAPITAL ALLOWANCE (AUTOMATION CA) FOR MANUFACTURING AND SERVICES SECTORS

Manufacturers involved in innovative and productive activities eligible for an Automation Capital Allowance (Accelerated Capital Allowance) of 200% on the first RM10 million of qualifying capital expenditure.

Automation Capital Allowance (Automation CA) For Manufacturing And Services Sectors

1) Objective:

The Automation Capital Allowance (Automation CA) was introduced to encourage adoption of automation among manufacturing companies.

2) Tax Incentive

Categories

Tax Incentive

1.

High labour-intensive industries (rubber products, plastics, wood, furniture and textiles)

2.

Other industries including Service Sector

Automation CA of 200% on the first RM10 million in qualifying expenditure incurred within year of assessment from 2023 to 2027.

3) Eligibility Criteria

  • Companies must be incorporated under the Companies Act 2016;
  • Tax residents of Malaysia;
  • Companies must have been operating in manufacturing or services activities for a minimum of 36 months;
  • The company must incur expenditures for at least one (1) machinery /equipment / software / system with an adaptation of Industry 4.0 within the eligible amount of RM10 million
  • Industry 4.0 elements:

This incentive is eligible to be considered for application received by MIDA from 1st January 2023 until 31st December 2027.

Categories
Featured Ideas & Insights

Incentive For Reinvestment Under New Industrial Master Plan (NIMP) 2030

Incentive For Reinvestment Under New Industrial MasterPlan (NIMP) 2030

New Industrial Master Plan (NIMP) 2023 offers reinvestment incentive with two tiers. Tier 1 providing Investment Tax Allowance (“ITA”) of 100% qualifying capital expenditure (“QCE”) against 100% of statutory income and Tier 2 offering ITA of 60% QCE against 70% of statutory income. This incentive is designed to encourage existing companies to reinvest in high-growth and high-value activities.

Incentive For Reinvestment Under New Industrial Master Plan (NIMP) 2030

  1. Malaysian government has introduced a reinvestment incentive aligned with the New Industrial Master Plan (NIMP) 2030, featuring a tiered and outcome-driven framework.
  2. Objectives of the incentive are:
    • To motivate companies to invest in sectors with high growth potential and substantial value.
    • To ensure that the tax incentives provided by the Government support the achievement of the targeted outcomes under the NIMP 2030 and further stimulate national economic growth.
  3. This incentive provides an opportunity for existing companies that have exhausted their Reinvestment Allowance, to continue to increase their capacity and investment in high-growth and high-value areas in the country.

A. Type of Incentives

  • The incentive is an Investment Tax Allowance (ITA) of 100% (or 60%) on the qualifying capital expenditure (excluding land cost) incurred for 5 years.
  • The allowance can be offset against up to 100% (or 70%) of statutory income for each assessment year until fully utilized.

B. Eligible Applicant

  • The company must be a Malaysian resident and incorporated in accordance with the Companies Act 2016.
  • Undertake expansion or diversification projects in the manufacturing sector.
  • The company eligible for only one (1) round of this reinvestment incentive.

C. Eligibility Criteria

List of product(s) or activity(ies) eligible for the reinvestment incentive as below:
  • Aerospace
  • Automotive
  • Chemical including biotechnology
  • Electrical & Electronics
  • Food Processing
  • Halal
  • Machinery & Equipment
  • Medical Devices
  • Metal
  • Mineral
  • Palm Oil-based Products
  • Pharmaceutical including biotechnology
  • Petroleum Products and Petrochemicals
  • Rail
  • Rubber-based Products
  • Ship building and Ship Repair
  • Textile, Apparel and Footwear
  • Wood, Paper and Furniture
The tiering tax incentive will be based on an outcome-based approach as follows:
Tier 1
Tier 2
Tax incentive
ITA of 100% on qualifying capital expenditure (QCE) (excluding land) and set off against 100% of statutory income.
ITA of 60% on QCE (excluding land) and set off against 100% of statutory income.
Incentive period
5 years
Minimum Conditions
  1. QCE must be incurred within the proposed 3-year period capital expenditure (excluding land) to be realised within 3 years as proposed;
  2. Implementation of Industrial Revolution 4.0 (IR4.0) technologies is required; and
  3. R&D expenditures (included related to product and technology improvement) must align with the proposed plan.
Additional Conditions
Subject to the following outcomes (but not limited to):

  1. Adequate number of newly hired Malaysian full-time employees in high-value positions (with minimum basic salary RM 10,000/month);
  2. The number of local and/or local service providers (companies incorporated in Malaysia) engaged as proposed;
  3. Adoption of green technology (generation of renewable energy or utilisation of energy efficiency equipment); and
  4. Any additional requirements for sustained economic growth, as stated in the approval letter.

Not Applicable.

D. Date of Application

Applications received by Malaysia Investment Development Authority (“MIDA”) from 1 January 2024 until 31 December 2028 are eligible to be considered for this incentive.
Categories
Featured Ideas & Insights

Johor-Singapore Special Economic Zone (JS-SEZ)

Johor-Singapore Special Economic Zone (JS-SEZ)

On 8 January 2025, Malaysia Government announced tax package incentive for The Johor-Singapore Special Economic Zone (JS-SEZ). JS-SEZ offers a special corporate tax rate 5% for up to 15 years for new investment in qualifying activities such as aerospace manufacturing, medical devices, global services hubs and artificial intelligence and also special personal income tax rate 15% for 10 years for knowledge worker.

Introduction

Johor-Singapore Special Economic Zone (JS-SEZ) is the first special economic zone spanning Southeast Asia’s borders located in the southern Malaysian state of Johor.

Effective from January 1, 2025, companies undertaking new investment in high-growth sectors within the JS-SEZ eligible to apply for special corporate tax rate of 5% for up to 15 years, 15% tax rate up to 10 years for knowledge workers employed in the JS-SEZ, stamp duty exemption etc.

Location

JS-SEZ-Flagship Area
Source: www.irda.com.my

Why Invest in JS-SEZ

Why JS-SEZ-01
Competitive Cost Advantage
Why JS-SEZ-02
Strong Government Support
Why JS-SEZ-03
Designated Flagships Areas
Why JS-SEZ-04
Strategic Location & Strong Connectivity
Why JS-SEZ-05
Attractive Policies & Incentives

Competitive Tax Incentive

A. Special Tax Corporate Tax Rate:

Special tax rate of 5% for up to 15 years for companies undertaking new investment as below:

No.

Category
Type of Incentive
1.
Flagship F (Kulai – Sedenak)

Manufacturing Company:
  1. Artificial Intelligence (AI), Quantum Computing Supply Chain;
  2. Medical Devices; or
  3. Pharmaceuticals.

Flagship E (Senai – Kulai)
Aerospace Manufacturing; and Maintenance Repair and Overhaul (MRO) Services.
JS-SEZ-table

2.

Flagship A (Johor Bahru Waterfront) and

Flagship B (Iskandar Puteri)
Global Service Hub.

Qualifying Services:
  1. Regional P&L;
  2. Strategic Business Planning;
  3. Corporate Development; and
  4. Regional or Global Treasury and Fund management conducting cash pooling activities via onshore intermediaries.
Special tax rate of 5% for a period of up to 15 years;

Eligibility Criteria / Conditions
  1. Annual operating expenditure of at least RM50 million;
  2. Company must Serve / Business Control of at least 10 Network Companies;
  3. Annual sales turnover of at least RM500 million and forex in-flow into the local banking system as proposed;
  4. A minimum of 50% of high-value positions (with a minimum monthly basic salary of RM10,000) shall be filled by full-time Malaysian employees as proposed.
3.
Flagship G (Desaru-Penawar)

Integrated Tourism Development
100% Investment Tax Allowance (ITA) on eligible capital expenditure (excluding land cost) for a period of 5 years. This allowance can be deducted up to 70% of statutory income for the relevant assessment year.

Eligibility Criteria / Conditions
  1. Company which does not have an existing entity or related entity undertaking same hotel or tourism project in Malaysia;
  2. Paid-up capital of at least RM2.5 million;
  3. Investment in capital expenditure (excluding land) of at least RM500 million;
  4. Company undertaking integrated tourism project which consists of the following:
    1. Hotel with minimum number of rooms of 80 which consists of standard, superior, deluxe and suite; and
    2. Minimum 1 tourist attractions (i.e. water park, outdoor park consists of rides and/or games, convention centre with capacity minimum of 3,000 participants, or outdoor sport excluding golf course and driving range).

4.

Flagship C (Tanjung Pelepas)

Smart Logistics Complex
Smart logistic operator who invests in development of smart logistics and carry out any of the eligible logistic activities:

a. Regional Distribution Hub;
b. Integrated Logistics Services;
c. Dangerous Goods Storage;
d. Cold Chain Facilities

100% Investment Tax Allowance (ITA) on eligible capital expenditure (excluding land cost) for a period of 5 years. This allowance is deducted up to 100% of the statutory income for the relevant assessment year.

Eligibility Criteria / Conditions

  1. Investment in capital expenditure (excluding land) of at least RM500 million;
  2. The built-up area of the smart warehouse complex must be at least 50,000m2 and equipped with at least three (3) enabling elements technologies under the IR4.0;
  3. Use the application of modern construction techniques i.e. achieving a score for the Industrial Building System (IBS) that has been set by the Construction Industry Development Board (CIDB)
  4. Total full-time workforce must consist of at least 80% Malaysian citizens;
  5. A minimum of 30% of total high-value positions (with a minimum basic salary of RM10,000) shall be filled by full-time Malaysian employees.
5.
Flagship D (Tanjung Langsat – Kong-Kong)

Manufacturing – Downstream Specialty Chemicals
Eligible product(s) / activity(ies):
a. Base Chemicals;
b. Organic intermediates C1 to C6
c. Specialty chemicals;
d. Fertilizers;
e. Polymers / Plastics;
f. Oleo chemical / Biochemical.
Special tax rate of 5% or 10% for a period of up to 10 years, for A company with capital investment (excluding land) of RM500 million and above in the manufacturing sector; OR
60% or 100% Investment Tax Allowance (“ITA”) on eligible capital expenditure (excluding land cost) for a period of 10 years.

Eligibility Criteria / Conditions
  1. A new company or an existing company undertaking diversification activities in relation to the eligible activities / products under this cluster;
  2. The company is required to have a minimum paid-up capital of RM2.5 million at the point of submission of application to MIDA;
6.
Additional Incentives
  1. 40% stamp duty exemption on the instrument of transfer/ financing agreement for the purchase of a commercial property in Flagship A and B that remains unsold as at 31st December 2024. The stamp duty exemption to be provided under Section 80(1) under the Stamp Act 1949;
  2. A deduction equivalent to amount not exceeding RM1 million for each year assessment in respect of cash contribution or contribution in-kind by qualifying person who sponsors a hallmark event.
  3. The hallmark event referred to is an event of regional or international significance which is carried on in Flagship G and supported/ verified by MOTAC. For contribution made between 1 January 2025 to 31 December 2034.
  4. ACA in respect of renovation costs incurred on a building or part of a commercial building located in Flagship A-G for the purpose of qualifying company’s business. Qualifying companies are companies that have been approved any tax incentives under PIA 1986 or ITA 1967 between 1 Jan 202 – 31 December 2034 and operating in Flagship A-G. This incentive to be utilized only once throughout their business operation in JS-SEZ.

To include expenses on:
  • General electrical installation
  • Lighting
  • Gas system
  • Water system; Kitchen fittings
  • Sanitary fittings
  • Door, gate, window, grill and roller shutter
  • Fixed partitions
  • Flooring (including carpets)
  • Wall covering (including paint work)
  • Incentives & Eligibility Criteria
  • False ceiling and cornices
  • Ornamental features or decorations excluding fine art
  • Canopy or awning
  • Recreation room for employee
  • Air-conditioning system
  • Day care centre for employees’ children
  • Surau
  • Reception area
  • Green elements, smart solutions systems

Initial Allowance: 20%, Annual Allowance: 40%

B. Special Tax Rate for Knowledge Workers:

A special tax rate of 15% for a period of 10 years is provided for eligible knowledge workers in all Flagships.

Eligibility Criteria / Conditions:

  1. Malaysian/Non-Malaysian citizen;
  2. Not generating employment income in Malaysia 24-months prior;
  3. Salary abroad/in Malaysia >RM20,000 per month.
  4. Subject to academic qualifications / years of professional work experience
  5. Subject to MyCOL profession and JS-SEZ qualifying sectors
Source: MIDA guideline
Categories
Featured Ideas & Insights

Malaysia Green Investment Tax Allowance (GITA) For Own Comsumption

MALAYSIA GREEN INVESTMENT TAX ALLOWANCE (GITA) FOR OWN COMSUMPTION

Companies undertake in green technology project for own consumption may enjoy up to 100% Green Investment Tax Allowance (“GITA”) to be offset against 70% of statutory income. Promoted activities such as green building, renewable energy system, energy efficiency, battery energy storage system, electric vehicles etc.

In 2024 Budget, the green technology tax incentives have been revised to the following categories:

The Malaysian Green Technology and Climate Change Corporation (MGTC) has issued a new guideline for GITA for own consumption project as below:

(i) Investment Tax Allowance :

Tier 1

Tier 2

Qualifying Activities

Qualifying asset as approved by Minister of Finance, Battery Energy Storage System (BESS) and Green Building.

Qualifying asset as approved by Minister of Finance (Appendix 11), Renewable Energy System and Energy Efficiency (Appendix 2).

Percentage of GITA

100%

60%

Percentage (%) of Statutory
Income to be Set-Off

70%

70%

Qualifying CAPEX

  • The qualifying capital expenditure must be an approved asset by MOF that have been verified by MGTC and is listed under the MyHIJAU Directory;
  • For Green Building, the qualifying CAPEX must be verified by the locally Green Building Rating Tools/ Certification Body approved by Government;
  • The asset must be new and owned by the Company;
  • The asset must be used in the business carried out by the company in Malaysia for own consumption and not for income generation.

Qualifying asset

  • Electric vehicles (for commercial / industrial used only);
  • EV Infrastructure;
  • Green Building;
  • Energy Storage
  • Energy Efficiency;
  • Renewable Energy System;
  • Waste Composter or waste recycling;
  • Wastewater recycling or rainwater
  • harvesting

Incentive Period

Qualifying Capital Expenditure incurred starting from 1 January 2024 until 31

December 2026.

Application period

The application made under the GITA Asset Guidelines must be received by the Malaysian Green Technology and Climate Change Corporation [“MGTC”] from 1st January 2024 until 31st December 2026.

(ii) Eligibility criteria:

a) New or existing Company:

  • A newly established company that incurred qualifying capital expenditure under GITA Asset; OR
  • Existing Company operating in Malaysia but has not incurred qualifying capital under GITA Asset and has not been approved for Green Technology Incentive.


b) Companies within the same group incurring the qualifying capital expenditure:

  • The project carried out in building/location separately from activities carried out by holding company or related companies;
  • The plant, machinery and equipment used shall be separately used and shall not be transferred from holding company or related companies;
  • Not shares the same employees as per holding company or related companies except for the management staff and directors of the Company;
  • This project must not result in a reduction in the investment of holding company or related companies.


c) To comply all the following criteria:

  • Minimize the degradation of the environment or reduce greenhouse emission;
  • Promotes health and improvement of environment; and
  • Conserves the use of energy, water and/or other forms of natural resources or promote the use of renewable energy or able to recycle waste material resources.
Categories
Featured Ideas & Insights

Malaysia Cold Chain Facilities

Malaysia Cold Chain Facilities

Investment in cold chain facilities or providing services for perishable agricultural produce such as fruits, vegetables, flowers, ferns, meat and aquatic products eligible for tax exemption up to 70% of statutory income or Investment Tax Allowance of 60% up to 5 years.

Tax Exemption for Companies Providing Cold Chain Facilities

Companies providing cold chain facilities and services for perishable agricultural products i.e. fruits, vegetables, flowers, ferns,
meat and aquatic products are eligible for:

Type of Company
Incentive
New Company
  • Pioneer Status with tax exemption of 70% of statutory income for a period of 5 years;
  • Unabsorbed pioneer losses after the end of pioneer period are allowed to be carried forward for 7 consecutive year of assessments;

    OR
  • Investment Tax Allowance (ITA) of 60% on the qualifying capital expenditure incurred for 5 years;
  • Unutilised allowances can be carried forward until fully absorbed.
Existing Company
(Company intend to reinvest in cold chain facilities for perishable agricultural produce)
  • Pioneer Status with tax exemption of 70% of increased statutory income for
    a period of 5 years;
  • Unabsorbed pioneer losses after the end of pioneer period are allowed to be
    carried forward for 7 consecutive year of assessments;

    OR
  • Investment Tax Allowance (ITA) of 60% on the additional qualifying capital
    expenditure for 5 years;
  • Unutilised allowances can be carried forward until fully absorbed.
Eligible Company
Eligible Activities
  • Must be Independent Service Provider (i.e the company conducts all of the cold chain activities on its own);
  • At least 60% of the company’s revenue must be derived from the provision of cold room facilities, refrigerated transportation and other related services for local agriculture produce.
  • Provision of cold room facilities or refrigerated transportation for local agricultural produce with or without other post-harvest activities including cleaning, washing, grading, freezing/chilling and packing;
  • Provision of cold room facilities or refrigerated transportation for local processed food products.
Categories
Featured Ideas & Insights

Why Dubai

Why Dubai

The UAE’s 0% corporate tax policy transcends numbers; it’s an invitation to transform your business aspirations into reality. With a robust infrastructure, a strategic location, and a welcoming environment, the UAE beckons entrepreneurs and visionaries to harness its potential.

One of the LOWEST TAX RATES in the world, embracing 0% Corporate Tax in the UAE

The United Arab Emirates (UAE) stands as a global beacon of business innovation and prosperity. In the heart of this thriving economic landscape, the UAE offers an array of incentives and advantages to both local and international companies. At the core of this allure is the UAE’s corporate tax policy, a game-changer that propels businesses towards uncharted heights.

Tax Exemptions for Companies in Dubai vs Malaysia

Why Dubai-Tax Exemption.jpg
Tax
Rate
Conditions
Value-Added Tax (VAT)
While the UAE champions business freedom, it maintains a balanced approach with a 5% VAT rate, obliging businesses with revenue exceeding AED 375,000 Yet, the UAE’s commitment to global trade is evident as exports of goods remain untaxed, fostering an environment ripe for international commerce.
5%
0%
Businesses with revenue > AED 375,000 (USD 102,000)
Export of goods
Value-Added Tax (VAT)
In the UAE, the benefits extend beyond corporate tax. Dividends, capital gains, intragroup transactions, and reorganizations all enjoy a tax rate of 0%, fostering an ecosystem where business can flourish without restraint.
0%
Dividend and Capital gain, as well as intragroup transaction and reorganisations.
Categories
Featured Ideas & Insights

Servicing Singapore from Outsourcing Office in Malaysia

Servicing Singapore from Outsourcing Office in Malaysia

In today’s global economy, working from home is no longer a foreign concept. However, employees may feel isolated when working alone. We have a solution for Companies who are interested in establishing an outsourcing office in Malaysia for their Singapore work. Let us help you in managing payroll, leave records, utilities supply, furnishing the office and compliance matters.

Servicing Singapore from Outsourcing Office in Malaysia

Let us be your partner to manage your work from Malaysia home employees, from payroll, leave records, utilities supply, fully furnished outsourcing office, compliances to law and regulations.
Servicing Singapore from Outsourcing Office in Malaysia
Work from Malaysia Home
Work from Outsourcing Office (WFOO) in Malaysia
Categories
Featured Ideas & Insights

Why Singapore?

Why Singapore?

Singapore is a strategic base to implement your growth strategies and to manage and integrate your operations for the region and beyond. Being one of the lowest income tax rate countries, Singapore has further announced a full and partial tax exemption for the newly incorporated company for the first 3 years consecutively.

1) One of the LOWEST TAX RATES in the world

With effect from 2010, Singapore corporate income tax rate has further reduced from 18% to 17%, being one of the lowest tax rates in the world.
Singapore Government has declared a new start-up tax exemption for newly incorporated and partial tax exemption for existing companies:

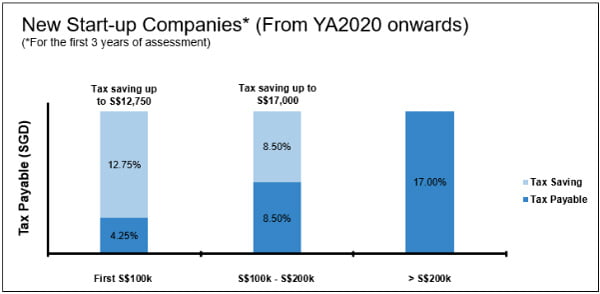
Tax Exemptions for Newly Start-up Companies in Singapore
why singapore-01

4.25% tax on first S$100K chargeable income

For a newly incorporated company (1), the corporate income tax rate is 4.25% on the first S$100k of chargeable income for the first 3 years of assessment consecutively.

8.50% tax on chargeable income of above S$100K up to S$200K

The newly incorporated companies are continued to enjoy for the partial tax exemption which effectively translates to about 8.50% tax rate on chargeable income of above S$100,000 up to S$200,000 per annum. The chargeable income above S$200,000 will be charged at the normal headline corporate tax rate of 17%.
Tax Exemptions for Existing Companies in Singapore
why singapore
The 4th years of assessment and onwards, the companies pay only 4.25% tax on their first S$10,000 of chargeable Income and 8.50% for the next S$190,000. The chargeable income above S$200,000 will be charged at the normal headline corporate tax rate of 17%.

2) Engage in TRIANGULAR or TETRAGONAL trade

The companies engaged in international transactions among two or more countries, for instance, the companies purchase goods from e.g. China, and then sell them to e.g. America or trade domestically, Malaysia. This is when the companies need a lower tax trading company (2) to act as the intermediary to issue invoice and packing list in order to strengthen their competitive power in the international or local market.

3) Government Incentives

Overview of government incentives

Depending on your company’s business plans, you may consider various tax incentives and grants as follows:
Internationalisation
Incentives available
Benefits
International Headquarters (IHQ) Award
Concessionary corporate tax rates of 5% or 10% for companies that commit to anchor substantive HQ activities in Singapore to manage, coordinate and control regional business operations. The award is accompanied with the award of Development and Expansion Incentive governed by Singapore Economic Development Board (EDB).
Mergers & Acquisitions (M&A) Scheme
The acquiring company is entitled to the following benefits:
  • 25% of M&A allowance (capped at S$10 million) of the total acquisition value capped at S$40 million per YA.
  • Double Tax Deduction (DTD) on the transaction cost capped at S$100,000 incurred during the share acquisition process.
Double Tax Deduction (DTD) for Internationalisation Scheme
Enjoy up to 200% tax deduction on qualifying expenditure incurred on market expansion and investment development activities.

The qualifying expenditures include:
  • Qualifying salary expenses incurred for employees posted overseas in an overseas entity
  • Overseas business development trips and missions
  • Overseas investment study trips and missions
  • Overseas trade fairs
  • Local trade fairs approved by Enterprise Singapore or STB
Market Readiness Assistance (MRA) grant
Funding support of 50% of eligible costs, capped at S$100,000 per company per new market by Enterprise Singapore. The eligible costs for marketing activities including overseas market set-up, business development and market promotion.
Trading
Incentives Available
Benefits
Global Trader Programme
A concessionary corporate tax rate of 5% or 10% for a renewable 3 or 5-year period on qualifying trading income granted by Enterprise Singapore, which includes income from physical trading, brokering of physical trades, derivative trading income, and income from structured commodity financing activities, treasury activities and advisory services in relation to mergers and acquisitions.
Manufacturing and Services
Incentives Available
Benefits
Pioneer Incentive
Tax exemption on income from qualifying activities for a period of not exceeding 15 years, administered by Economic and Development Board (EDB).
Development & Expansion Incentive (DEI)
Reduced tax rate of 5% or 10% on incremental income from qualifying activities, limited to 5 years. The incentive is governed by Economic and Development Board (EDB).
Investment Allowance (IA)
Allowance of up to 100% (on top of normal capital allowance) on approved fixed capital expenditure. This incentive is administered by Economic and Development Board (EDB).
Integrated Investment Allowance (IIA)
Additional allowance on fixed capital expenditure incurred on qualifying productive equipment placed with an overseas company for an approved project. This scheme is administered by Economic and Development Board (EDB).
Land Intensification Allowance (LIA)
Initial allowance of 25% and annual allowance of 5% on qualifying capital expenditure incurred for the construction or renovation/extension of a qualifying building or structure. Annual allowances of 5% are granted until total allowance amounts to 100% of qualifying capital expenditure. Approvals for the incentive will be granted by the Economic Development Board (EDB).
Automation Support Package(under Enterprise Singapore)
  • Capability Development Grant (CDG)
  • Investment Allowance (IA)
  • Enhanced SME Equipment Loan
Grant support up to 70% of qualifying project costs such as equipment, training and consultancy.

Qualifying projects may be eligible for an IA of 100% on the amount of approved capital expenditure, net of grants. The approved capital expenditure is capped at S$10 million per project.

Under Enterprise Financing Scheme (EFS), qualifying SMEs may receive up to 70% government’s risk-share with participating financial institutions for qualifying projects. SMEs can apply for fixed asset loans of up to S$30 million.
Financial and Treasury
Incentives Available
Benefits
Finance & Treasury Centre (FTC) Incentive
Enjoy concessionary corporate tax rate of 8% for five years on income derived from qualifying services/ activities as well as withholding tax exemption on interest payments on loans from banks and approved network companies for FTC activities. This incentive is administered by Economic and Development Board (EDB).
Financial Sector Incentive (FSI)
Concessionary tax rate of 10% or 13.5% for licensed financial institutions, from large universal banks, fund managers to capital market players. This incentive is governed by Monetary Authority of Singapore (MAS).
Research and Development (R&D) and intellectual property (IP) management
Incentives Available
Benefits
Research Incentive Scheme for Companies (RISC)
Co-funding to encourage and assist businesses companies in Singapore to conduct or expand their research and development (R&D) activities in science and technology. This scheme is administered by Economic and Development Board (EDB).

Supportable project costs include expenditure in the following:
  • Manpower cost (up to 50% support)
  • Equipment, materials, consumables and software (up to 30% support)
  • Singapore-based professional services (up to 30% support)
  • IPRs, e.g. licensing, royalties, technology acquisition (up to 30% support)
Intellectual Property Development Incentive (IDI)
Reduced tax rate of 5% or 10% on a percentage of qualifying IP income for an initial period of not exceeding 10 years, and may be further extended for a period or periods not exceeding ten years each. This incentive is administered by Economic and Development Board (EDB).
Approved Foreign Loan Incentive (AFL)
Reduced or nil withholding tax rate on interest payments on loans with minimum amount of S$20 million taken to purchase productive equipment. This incentive is administered by Economic and Development Board (EDB).
Approved royalties incentive (ARI)
Reduced or nil withholding tax rate on approved royalties, fees or contributions to research and development costs made to a non-tax resident.. This incentive is administered by Economic and Development Board (EDB).
Writing-down allowances for IP acquisition (S19B)
Automatic 5/10/15-year writing-down allowances on capital expenditure incurred for IPR acquisitions with legal and economic ownership. EDB’s approval is required if only economic ownership of IP rights is acquired.
Maritime, shipping and logistics
Incentives Available
Benefits
Maritime Sector Incentive (MSI) – Singapore Registry of Ships (MSI-SRS) and Approved International Shipping (MSI-AIS)
Tax exemption on qualifying shipping income from operating Singapore and foreign- flagged ships, provision of specified ship management services, and income from foreign exchange and risk management activities which are carried out in connection with or incidental to the operations of ships for either a 10-year renewable period; or a 5-year non-renewable period, with the option of graduating to the 10-year renewable award at the end of the 5-year period. This incentive is administered by Maritime and Port Authority of Singapore (MPA).
MSI – Shipping Related Support Services (MSI-SSS) Award
Concessionary tax rate of 10% on the incremental income derived from carrying out approved shipping-related support services for a 5-year renewable period. This incentive is administered by Maritime and Port Authority of Singapore (MPA).
  • Ship broking;
  • Forward freight agreement (FFA) trading;
  • Ship management;
  • Ship agency;
  • Freight forwarding and logistics services; and
  • Corporate services rendered to qualifying approved related parties who are carrying on business of shipping – related activities.
MSI – Maritime Leasing (MSI-ML) Award
Concessionary tax rate of 10% for up to 5 years on qualifying leasing or management income. This incentive is administered by Maritime and Port Authority of Singapore (MPA). This incentive is administered by Maritime and Port Authority of Singapore (MPA).
Maritime Innovation & Technology (MINT) Fund
To promotes and encourages upstream research, product and solution development relevant to the maritime industry in Singapore. This incentive is administered by Maritime and Port Authority of Singapore (MPA).

Grant of up to 70% of the total qualifying project costs (inclusive of input GST), comprising of manpower and equipment either engaged or acquired for the purposes of the project, and other operating expenditure incurred for the purposes of the project.

4) TAX EXEMPTION ON DIVIDEND DECLARED FROM SINGAPORE

Dividend declared out of the profit derived from Singapore Company and received in Malaysia is exempted from tax(3).

5) TAX TREATIES

Singapore has entered into Double Taxation Agreement (“DTA”) with 88 countries. Please refer to APPENDIX I.

6) AUDIT EXEMPTION of a Singapore Company

A company incorporated on or after 1 July 2015, if a private company that fulfils at least two of the following three quantitative criteria in each of the immediate past two financial years is exempted from audit (4) : (a) Total annual revenue of not more than SGD 10 million; (b) Total assets of not more than SGD 10 million; (c) Number of employee of not more than 50.
1. a) It is incorporated in Singapore and a tax resident of Singapore for that Year of Assessment. b) It has no more than 20 shareholders throughout the basis period relating to that Year of Assessment and all its shareholders are individuals throughout the basis period relating to that Year of Assessment; or there is at least one individual shareholder with a minimum of 10% shareholding. c) Its principal activity is not related to (i) investment holding, or (ii) property developer for sales, investment, or both.

2. To consider a company as resident in Singapore, the control and management of the business must be exercised in Singapore. Though the term “control and management” is not clearly defined by authorities, a generally accepted consensus is that it refers to the policy level decision making at the level of Board of Directors and not the day-to-day decision making and operations.

3. Section 127 (1) – Exemptions from tax. Any income specified in Part 1 of Schedule 6 shall be exempt from tax. Part 1 Schedule 6, para 28 (1), Income of any person, other than a resident company carrying on the business of banking, insurance or sea or air transport, for the basis year of assessment derived from sources outside Malaysia and received in Malaysia Part 1 schedule 6, para 28(1), exempt income of any person derive from sources outside Malaysia and received in Malaysia (See also exception).

4. Existing safeguards will however be retained, such as requiring all companies to keep proper accounting records, and empowering shareholders with at least 5% voting rights to require a company to prepare audited accounts.

Double Taxation Agreement

APPENDIX I

Albania Jersey Slovak Republic
Australia Kazakhstan Slovenia
Austria South Korea South Africa
Bahrain Kuwait Spain
Bangladesh Laos Sri Lanka
Barbados Latvia Sweden
Belarus Libya Switzerland
Belgium Liechtenstein Taiwan
Brunei Lithuania Thailand
Bulgaria Luxembourg Tunisia
Cambodia Malaysia Turkey
Canada Malta Turkmenistan
China Mauritius Ukraine
Cyprus Mexico United Arab Emirates
Czech Republic Mongolia United Kingdom
Denmark Morocco Uruguay
Ecuador Myanmar Uzbekistan
Egypt Netherlands Vietnam
Estonia New Zealand Bahrain*
Ethiopia Nigeria Brazil*
Fiji Norway Chile*
Finland Oman Hong Kong*
France Pakistan Oman*
Georgia Panama Saudi Arabia*
Germany Papua New Guinea United Arab Emirates*
Ghana Philippines United States of America*
Guernsey Poland Bermuda**
Hungary Portugal United States of America**
India Qatar Armenia***
Indonesia Romania Brazil***
Ireland Russian Federation Gabon***
Isle of Man Rwanda Germany***
Israel San Marino Greece***
Italy Saudi Arabia Indonesia***
Japan Seychelles Kenya***

Note:
* Limited Treaties
** Exchange of Information Arrangements
*** Agreements Which Are Signed But Not Ratified

Categories
Featured Ideas & Insights

Why Labuan?

Why Labuan?

If your business model may optimise use of offshore structure, so why might an onshore investment if it carries lesser advantages as compared to offshore investment? The Labuan  company is only taxed at 3% on its audited profit.

TAX BENEFITS

1. Corporate Tax 3%

A. The Labuan Business Activity Tax (Requirements for Labuan Business Activity) Regulation 2021 has been gazetted on 22 November 2021 and are deemed to have come into operation on 1 January 2019, a Labuan company carrying on a Labuan business activity is only subject to tax at the rate of 3% of net profit PROVIDED that it has fulfilled the requirement of the number of full time employees and an amount of annual operating expenditure as specified in the Schedule below:

Labuan Company Carrying on a Labuan Business Activity

Minimum Number of Full Time Employees in Labuan

Minimum Amount of Annual Operating Expenditure in Labuan (RM)

Labuan Insurer, Labuan reinsurer, Labuan takaful operator or Labuan retakaful operator

3

200,000

Labuan underwriting manager or Labuan underwriting takaful manage

4

100,000

Labuan insurance manager or Labuan takaful manager

4
100,000

Labuan insurance broker or Labuan takaful broker

2

100,000

Labuan captive insurer or Labuan captive takaful –
  1. Labuan first party captive insurer or Labuan first party captive takaful; or
  2. Labuan third party captive insurer or Labuan third party captive takaful.
2
2

100,000

100,000

Labuan bank, Labuan investment bank, Labuan Islamic bank or Labuan Islamic investment bank

3

200,000

Labuan trust company

3

120,000

Labuan leasing company or Labuan Islamic leasing company

  1. 10 or less related Labuan leasing companies or Labuan Islamic leasing companies;
2 per group
100,000 for each Labuan leasing company or Labuan Islamic leasing companies;
  1. 11 to 20 related Labuan leasing companies or Labuan Islamic leasing companies;
3 per group
100,000 for each Labuan leasing company or Labuan Islamic leasing companies;
  1. 21 to 30 related leasing companies or Labuan Islamic leasing companies;

4 per group

100,000 for each Labuan leasing company or Labuan Islamic leasing companies;
  1. More than 30 related Labuan leasing companies or Labuan Islamic leasing companies
Increase of 1 employee for every additional 10 related companies or Labuan Islamic leasing companies;
100,000 for each Labuan leasing company or Labuan Islamic leasing companies;

Labuan credit token company or Labuan Islamic credit token company

2

100,000

Labuan development finance company or Labuan Islamic development finance company

2

100,000

Labuan building credit company or Labuan Islamic factoring company

2

100,000

Labuan factoring company or Labuan Islamic factoring company

2

100,000

Labuan money broker or Labuan Islamic factoring company

2

100,000

Labuan fund manager

2

100,000

Labuan securities license or Labuan Islamic securities license

2

100,000

Labuan fund administrator

2

100,000

Labuan company management

Provision of treasury processing services and such other services as defined in Section 129 of the Labuan Financial Services and Securities Act 2010.

2

100,000

Labuan International Financial Exchange

2

120,000

Self-regulatory organisation or Islamic self-regulation organisation

2

120,000
Labuan entity that carries on any one or more of the following business activity:
  1. Administrative services
    • Services pertaining to employee management, payroll management, property management, human resource management, financial planning, contract or subcontract management, facilities management or proposal management.*
  2. Accounting services
    • Services pertaining to recording, analysing, summarizing or classifying financial, commercial and business transactions and information of a person or business.*
  3. Legal services
    • conveyancing services ;*
    • legal advisory services ;*
    • litigation or legal representation services in any proceedings before any court, tribunal or other authority ;or *
    • legal dispute resolution services including alternative dispute resolution. *
  4. Backroom processing services
    • services relating to settlements of receivables and payables, clearance, record maintenance, regulatory compliance or information technology (IT) related services which are usually performed by administration and support personnel who do not deal directly with client. *
  5. Payroll services
    • services relating to:- processing, calculation, payment and deduction of remuneration, benefits, tax and statutory payment ; or
    • issuance of payslip and tax statement *
  6. Talent management services;
    • services relating to the provision of human resource services to attract, onboard, develop, motivate, and retain employees.*
  7. Agency services ;
    • services relating to the provision of specific services on behalf of another group, business, or person pursuant to an agency agreement between the agent and its client.*
  8. Insolvency related services;
    • services related to administering company liquidations or winding up or personal bankruptcy.*
  9. Management services other than Labuan company management under item 17
    • organization and coordination of activities of a business in order to provide services to the clients and usually consist of organizing, supervising, monitoring, planning, controlling and directing business’s resources such as human, financial and technology*
*As per Frequently-Asked Questions (FAQ) on Labuan Business Activity Tax (Requirements for Labuan Business Activity) Regulations 2021 [P.U. (A) 423/2021] issued by Labuan Financial Services Authority (LOFSA) dated 14 December 2021.*
2

50,000

Labuan entity that undertakes investment holding activities other than pure equity holding activities
1

20,000

Labuan entity that undertakes pure equity holding activities
Exempted under the Labuan Business Activity Tax (Exemption) Order 2020 [P.U (A) 177/2020]

20,000

B. Management And Control Requirement For Labuan Entity That Undertakes Pure Equity Holding Activities

Regulation 3, The Labuan Business Activity Tax (Requirements for Labuan Business Activity) Regulation 2021 which is deemed to have come into operation on 1 January 2021, requires the above mentioned company to comply with the following:

  1. meeting of the board of directors is convened in Labuan at least once a year;
  2. the registered office of the Labuan entity shall be situated in Labuan;
  3. the secretary of the Labuan entity appointed under the Labuan Companies Act 1990 shall be resident in Labuan; and
  4. the accounting and business records including the minutes of meeting of the Labuan entity’s board of directors shall be kept in Labuan.

C. Income derived from intellectual property rights is subject to tax at the rate of 17% or 24% under Income Tax Acts 1967(“ITA”) .

With effect from 1 Jan 2019, under Income Tax (Deductions Not Allowed for Payment Made to Labuan Company by Resident) Rules 2018 (Amendment) 2020, the following type of payments made to a Labuan Entity by a company resident in Malaysia are not entitled to a tax deduction:

Type of payment

Amount not allowed for deduction

Interest payment

25%

Lease rental

25%

Other payments

97%

2) 0% ON SERVICE TAX AND 6 % ON IMPORTED SERVICE

No service tax shall be charged on any taxable service provided within or between Special Areas and Designated Areas unless on the taxable services prescribed in the Service Tax (Imposition of Tax for Taxable Service in Respect of Designated Areas and Special Areas) Order 2018.

3) 0% ON WITHHOLDING TAX

There is no withholding tax on dividends paid by a Labuan Company in respect of dividends distributed out of income derived from Labuan business activities or income exempt from income tax. Interest, royalties, lease rental, technical fee and management fees paid to a non-resident are not subject to withholding tax.

4) 0% ON STAMP DUTY

This may include but not limited to transfer of share, etc.

5) 100% EXEMPTION OF DIRECTOR’S FEE RECEIVED BY NON-CITIZENS INDIVIDUAL

6) DOUBLE TAXATION AGREEMENT (DTA) WITH MORE THAN 70 COUNTRIES

Labuan Company enjoys the benefits of more double taxation treaties than any other offshore company as it almost enjoys same full double taxation benefit as Malaysia company except for fourteen (14) of those 78 countries, and it can enjoy full treaty benefit even with those fourteen (14) countries by incorporating a Malaysian domestic subsidiary company.

Malaysia has entered into Double Taxation Agreements with various countries as follows:-
Double Taxation Agreements
^ Limited Agreements
# Income Tax Exemption Order
@ Synthesized text
Currently, Labuan has been specifically excluded from Double Taxation Agreement with the countries as follows:-
Double Taxation Agreements

7) LIBERAL LABUAN EXCHANGE CONTROL ENVIRONMENT – FREE FLOW OF FUNDS

8) INVESTMENT PROTECTION AGREEMENT (IGA) WITH MORE THAN 60 COUNTRIES

9) THE CONFIDENTIALITY OF COMPANY, SHAREHOLDER AND DIRECTORS’ INFORMATION IS ENSURED

10) LABUAN COMPANY VS BVI COMPANY

Labuan Company

BVI Company

Labuan is low-tax jurisdiction country.

BVI is tax-free jurisdiction country.

Certain home country may impose the income tax law on incomes deriving from offshore, if they have not been taxed offshore, particularly, when they are remitted back, this may appy to BVI Co but not Labuan Co as it pays minimum tax.

Labuan Co enjoys more than 70 countries’ double tax treaties (DTAs).

BVI enjoys only 2 countries’ (Japan and Switzerland) double tax treaties (DTAs), and these treaties are not used in practise.

Dividend declared from Labuan Co to Malaysia is free of tax.

Dividend declared from BVI co may subject to income tax.

Note: If the company is Non-Malaysian Co, the tax exemption will depend on each home country’s law jurisdiction and its double tax treaties with Malaysia.

No withholding tax on interest payment.

BVI has applied the European Union (EU) Savings Directive since 1 July 2005. A withholding tax (initially 15%, rising to 20% from 1 July 2008) has been applied to interest payments to natural persons resident within the EU.

Labuan has its registered auditor under its jurisdiction. The income tax payable is allowed to base on the audited profit, the source of income is cleared for reinvestment or dividend purpose, once it is paid.

BVI has no registered auditor under its jurisdiction.

ILLUSTRATIONS ON LABUAN COMPANY STRUCTURE

1) Labuan Leasing Company or Labuan Islamic Leasing Company

Suitable Industries
  • Vessel, aircraft, shipping, oil & gas, high value assets co.
Tax Advantages
  • Income tax is only 3% of net profit
  • Dividend income received by Labuan Co is exempted from tax.
  • No withholding tax on dividend declared And lease rental made by Malaysian subsidiaries or 3rd Party Malaysian Co.(2)
(1) A licence fee of RM60,000 (USD15,000) per year is only applicable in respect of leasing arrangements with Malaysian residents; no licence fee is payable if the Labuan Company is only carrying out leasing activities with non-Malaysian residents.

(2) If the company is Non-Malaysian Co, the tax exemption will depend on each home country’s law jurisdiction and its double tax treaties with Malaysia.

2) Investment Holding Company

Suitable Industries :

  • Investment holding or offshore investment.

Tax Advantages

  • Dividend income received by Malaysian Parent Co(1)  or Labuan Co is exempted from tax.
  • No withholding tax on dividend declared by Labuan Co to either Malaysian or Foreign Parent Co.
  • No withholding tax on interest charged by Malaysian or Foreign Parent Co to Labuan Co.
  • No Capital Gain Tax and stamp duty for the transfer of shares in Labuan Co, e.g. dispose the investment in Foreign Manufacturing Co by selling Labuan Co.
  • Enjoys double tax treaties with more than 70 countries via a Labuan Co.
(1) If the company is Non-Malaysian Co, the tax exemption will depend on each home country’s law jurisdiction and its double tax treaties with Malaysia.

3) Captive Insurance

Suitable Industries :

  • Captive Insurance

Tax Advantages

Income tax is only 3% of net profit

  • Dividend income received by Malaysian Parent Co(1) is exempted from tax.
  • No withholding tax on dividend declared by Labuan Captive Insurance Co.
  • Enjoys double tax treaties with more than 70 countries via a Labuan Co.
(1) If the company is Non-Malaysian Co, the tax exemption will depend on each home country’s law jurisdiction and its double tax treaties with Malaysia.

4) Offshore Financing

Suitable Industries :

  • Fund managers

Tax Advantages

  • Income from investment is exempted from tax for Labuan Co.
  • Dividend from Labuan Co is exempted from tax.
  • No withholding tax either on dividend declared by or interest charged from Labuan Co to Labuan Funds.
  • Distribution from Labuan Funds to investors is not subject to withholding tax.
  • Enjoys double tax treaties with more than 70 countries via a Labuan Co.

Other Advantages

  • Lower cost of funds.
  • Liberal Labuan exchange control environment.
  • Debt instruments of Labuan Co may be listed.
Investment Funds 投资基金
Islamic Financing 伊斯兰融资